A paradox of sovereignty: how the AES finances itself through the regional market
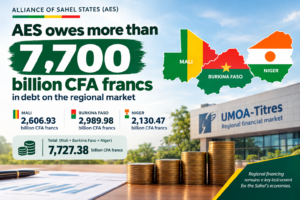
At the heart of the Alliance of Sahel States lies a persistent contradiction. The three member nations — Burkina Faso, Mali and Niger — have built their political identity around financial independence and a clean break from external dependencies. Yet as of 31 July 2026, their combined outstanding public securities on the West African regional market reached approximately 7,727 billion CFA francs, according to market data. This figure challenges the narrative of a sovereignty funded entirely from domestic resources.
The numbers behind the rhetoric
The political messaging has been consistent: sovereignty, a rupture from former dependencies, financing national efforts through own resources, and rejecting mechanisms seen as externally imposed. But the financial market data tells a more layered story.
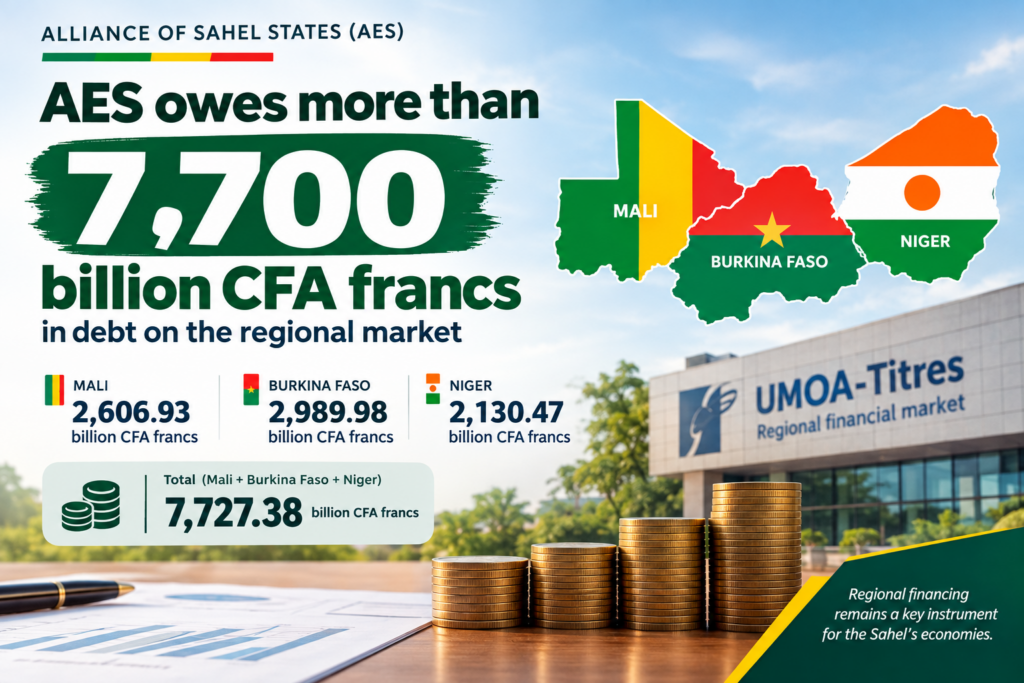
Available figures as of 31 July 2026 show that the three AES countries remain heavily active on the UMOA public securities market. On that date, the cumulative outstanding amounts stood at:
- Burkina Faso: 2,989.98 billion CFA francs
- Mali: 2,606.93 billion CFA francs
- Niger: 2,130.47 billion CFA francs
This totals 7,727.38 billion CFA francs.
These amounts do not represent a debt “owed to UEMOA” in an institutional sense. They are public securities still in circulation on the regional market. The distinction matters: states borrow from investors who purchase their bills and bonds. UMOA-Titres organises this very regional market designed to finance member states.
Burkina Faso: nearly 3,000 billion CFA francs outstanding
Burkina Faso recorded 2,989.98 billion CFA francs in outstanding securities on the regional market as of 31 July 2026.
The country accounts for roughly 12.4% of the total outstanding for all UMOA states, which stood at 24,073.53 billion CFA francs on the same date.
What makes this figure particularly notable is that Burkina Faso’s outstanding amount was still rising, up 2.46% over one month.
During the early months of 2026, Ouagadougou continued to raise funds on the regional market while simultaneously making repayments. In May alone, Burkina Faso mobilised 99.50 billion CFA francs in Treasury bonds and repaid 72.04 billion CFA francs.
In other words, regional financing has not disappeared with the sovereignty discourse: it remains a key instrument for treasury management and state financing.
Mali: over 2,600 billion CFA francs
Mali stood at 2,606.93 billion CFA francs in outstanding securities as of 31 July 2026.
This represents about 10.8% of the regional total.
Again, this is not a one-off phenomenon. UMOA-Titres data shows that by the end of May 2026, Mali’s outstanding amount had already reached 2,637.64 billion CFA francs. During that single month, Bamako mobilised 93.50 billion CFA francs, while repayments amounted to 110.07 billion CFA francs.
Mali was therefore simultaneously borrowing and repaying, following a standard debt management logic.
The real question is not simply whether Bamako borrows. It is at what pace, at what cost, and to finance which expenditures.
Niger: over 2,130 billion CFA francs
Niger recorded an outstanding amount of 2,130.47 billion CFA francs as of 31 July 2026, representing about 8.9% of the total UMOA outstanding.
It is the trajectory that demands the most attention.
Between April and May 2026, Niger’s outstanding amount jumped from 1,732.05 billion to 2,120.45 billion CFA francs — an increase of nearly 388.4 billion CFA francs in a single month, according to UMOA-Titres data.
This dramatic rise was driven largely by significant financing and debt reprofiling operations.
In May 2026, Niger mobilised 567.49 billion CFA francs, including 519.51 billion in Treasury bonds and 47.97 billion in bills, while repaying 191.31 billion CFA francs.
Days earlier, a large-scale operation allowed Niger to process 446.386 billion CFA francs in securities, including approximately 59.710 billion CFA francs in short-term securities repurchased to ease immediate treasury pressures. Net resources generated were estimated at around 327 billion CFA francs.
7,727 Billion CFA francs: the figure that unsettles
Adding the three outstanding amounts as of 31 July:
2,989.98 + 2,606.93 + 2,130.47 = 7,727.38 billion CFA francs.
In other words, nearly 7,727 billion CFA francs in public securities from the three AES countries remain in circulation on the regional market.
By comparison, all UMOA states together showed an outstanding amount of 24,073.53 billion CFA francs at that time.
The three AES countries alone therefore accounted for approximately 32.1% of the entire regional outstanding.
A contradiction with the sovereignty narrative?
This is where the real investigation begins.
It would be false to claim these three states are entirely dependent on the regional market. It would be equally false to suggest they have stopped using it.
The data demonstrates, on the contrary, a strong and persistent use of the regional financial market.
The market is not merely an external mechanism imposed on states: it has long been a normal channel for financing national budgets within the West African monetary space.
But a political and economic question remains: can a policy be presented as fully autonomous when several thousand billion CFA francs are raised from regional investors to fund state needs?
The answer requires looking beyond slogans.
The AES paradox
The paradox is even more striking since Burkina Faso, Mali and Niger withdrew from ECOWAS.
Politically, the three countries have asserted their intention to build an autonomous trajectory.
Financially, however, they continue to use the UMOA regional market.
And that market relies heavily on banks and investors from the West African space.
An analysis published in late 2025 noted a decline in exposure by investors from other UEMOA countries to AES state debt: their holdings fell from 3,174 billion to 2,801 billion CFA francs, a drop of 373 billion CFA francs between the fourth quarter of 2024 and the third quarter of 2025. Meanwhile, cross-holdings of securities among the three AES countries declined by 622 billion CFA francs, to approximately 3,160 billion CFA francs.
This phenomenon warrants monitoring: when investors become more cautious, financing can become more expensive and more difficult.
The true indicator: the cost of debt
The outstanding amount alone is not enough.
To judge the sustainability of this debt, one must also examine:
- interest rates;
- maturities;
- annual repayment amounts;
- tax mobilisation capacity;
- economic growth;
- the share devoted to security spending;
- the capacity to roll over maturing loans.
This is precisely where the risk lies.
A state can have a high but manageable outstanding amount if it has sufficient revenues and solid growth. Conversely, a state can face serious difficulties with a smaller debt if a large portion of securities matures simultaneously or if interest rates become too high.
Niger offers a glimpse of the problem
The Nigerien case perfectly illustrates this mechanism.
In May 2026, the country mobilised 567.49 billion CFA francs but also repaid 191.31 billion CFA francs.
Another operation involved 446.386 billion CFA francs, part of which was used precisely to repurchase maturing securities.
This means that some of the new resources do not necessarily constitute new money available to fund projects. They may serve to refinance existing debt.
This is a common mechanism on bond markets, but it must be stated clearly: raising several hundred billion does not automatically mean those hundreds of billions are added in full to resources available for development.
The trap of “billions mobilised” announcements
This is probably one of the most important points to retain.
When a government announces an issuance of 500 billion CFA francs, several questions must be asked:
- How much is genuinely new?
- How much serves to repay old securities?
- What is the interest rate?
- What is the duration?
- What will the total bill be for the taxpayer?
In Niger’s case, the May 2026 operation shows precisely why this distinction is essential: 446.386 billion CFA francs in gross amount processed, but approximately 327 billion CFA francs in net resources generated.
The difference is not an accounting detail. It completely changes the political reading of the figure.
Conclusion: sovereignty does not erase debt
The debate on the AES should not simply oppose “sovereignty” and “dependency.”
The numbers tell something more complex.
As of 31 July 2026, Burkina Faso, Mali and Niger cumulated 7,727.38 billion CFA francs in outstanding public securities on the UMOA regional market.
This is not a debt directly owed to UEMOA as an organisation. It is a debt to investors who subscribed to securities issued by these states.
But the observation remains: the three countries claiming greater financial autonomy continue to rely heavily on regional bond financing to cover their needs.
The real question is no longer whether the AES borrows.
It is how far these states can continue to borrow without the cost of this “financial sovereignty” ultimately weighing heavily on their future budgets.