A bold electrification drive with a lingering debt question
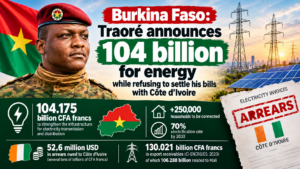
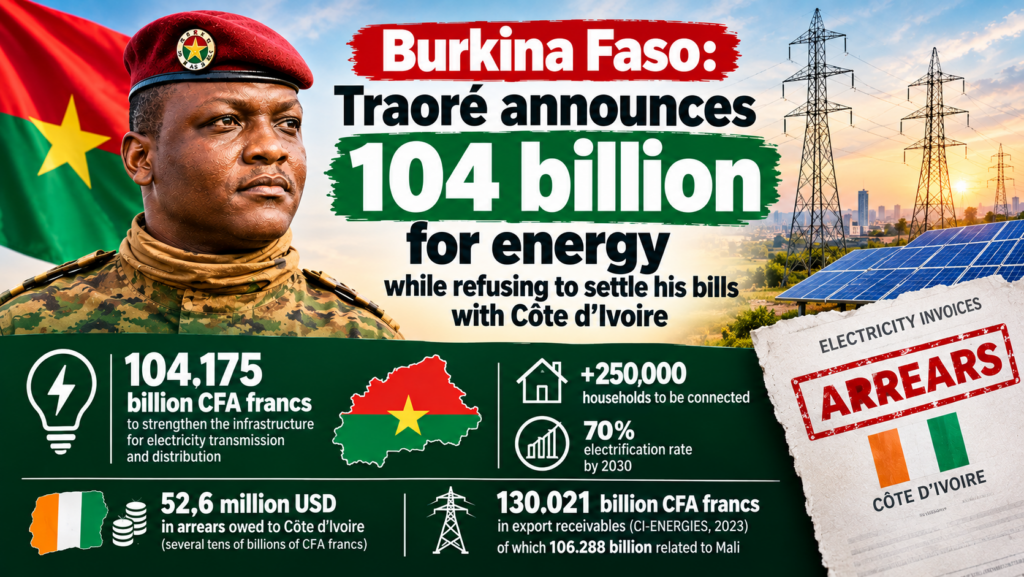
Burkina Faso’s government has approved a 104.175 billion CFA franc programme aimed at expanding electricity transport and distribution networks, connecting more than 250,000 households and lifting the electrification rate to 70 percent by 2030. The initiative falls under the national energy pact and the RELANCE 2026-2030 plan.
On paper, the figures are striking. Yet the announcement lands at a moment when the energy sector’s finances remain strained and the country continues to carry unpaid obligations toward Côte d’Ivoire.
The funding puzzle behind the headline number
The central question is not whether more electricity infrastructure is needed — it clearly is. The harder issue is where the money will come from and whether Burkina Faso’s financial credibility can support such an ambition.
Beyond the cost of new infrastructure, the country must also manage financial commitments already on its books. The International Monetary Fund, in its latest report on Burkina Faso, identified 52.6 million dollars in arrears owed to Côte d’Ivoire — equivalent to tens of billions of CFA francs. The IMF describes these as inherited external arrears, without reducing them to electricity imports alone.
That distinction matters. It does not, however, remove the underlying problem: a state seeking to strengthen its energy sovereignty must also be able to meet its financial obligations to its partners.
Côte d’Ivoire’s role in the regional power equation
Côte d’Ivoire has long been a key player in regional electricity exchanges. Documents from the African Development Bank highlight payment arrears from electricity-importing countries that weigh on the financial balance of the Ivorian sector. In 2023, CI-ENERGIES export receivables reached 130.021 billion CFA francs, of which 106.288 billion was linked to Mali.
Against this tense regional backdrop, the question shifts from the impact of the announcement to the discipline of financial management.
Sovereignty built on payments, not promises
Announcing more than 104 billion to electrify the country further may be legitimate and even necessary. But energy sovereignty is not decreed in speeches. It is built with power plants, networks, investments, paid suppliers and accounts capable of sustaining the stated policy.
This is where official discourse deserves to be tested against economic reality. Burkina Faso now presents reducing its energy dependence as a strategic priority. Its own national energy pact specifically plans to improve the sector’s financial viability and mobilise investment on a large scale.
The real challenge is therefore not only to promise 104 billion. It is to demonstrate that these funds will actually be raised, that the infrastructure will be delivered and that already accumulated financial commitments will be honoured.
Durable energy sovereignty cannot rest solely on a multiplication of announcements. It also requires the confidence of partners, the strength of public finances and respect for contractual obligations.
The contradiction that could undermine the plan
By presenting each new financing package as further proof of independence, Ibrahim Traoré’s government risks masking an essential contradiction: one cannot claim to build energy autonomy while leaving behind arrears that strain relations with the countries whose electricity and regional infrastructure still help keep the system running.
True energy sovereignty will begin when Burkina Faso can produce more, depend less on imports and, above all, pay its bills and honour its commitments.
Only then can the billions announced become something more than a political promise: a genuine, sustainable energy policy.